Every day, one story that matters, broken down into three numbered scenarios, each with its own probability. Never fixed — it shifts as the situation changes.
Scénario
Wednesday, actualité française
France: six vulnerabilities, a high-tension summer 2027
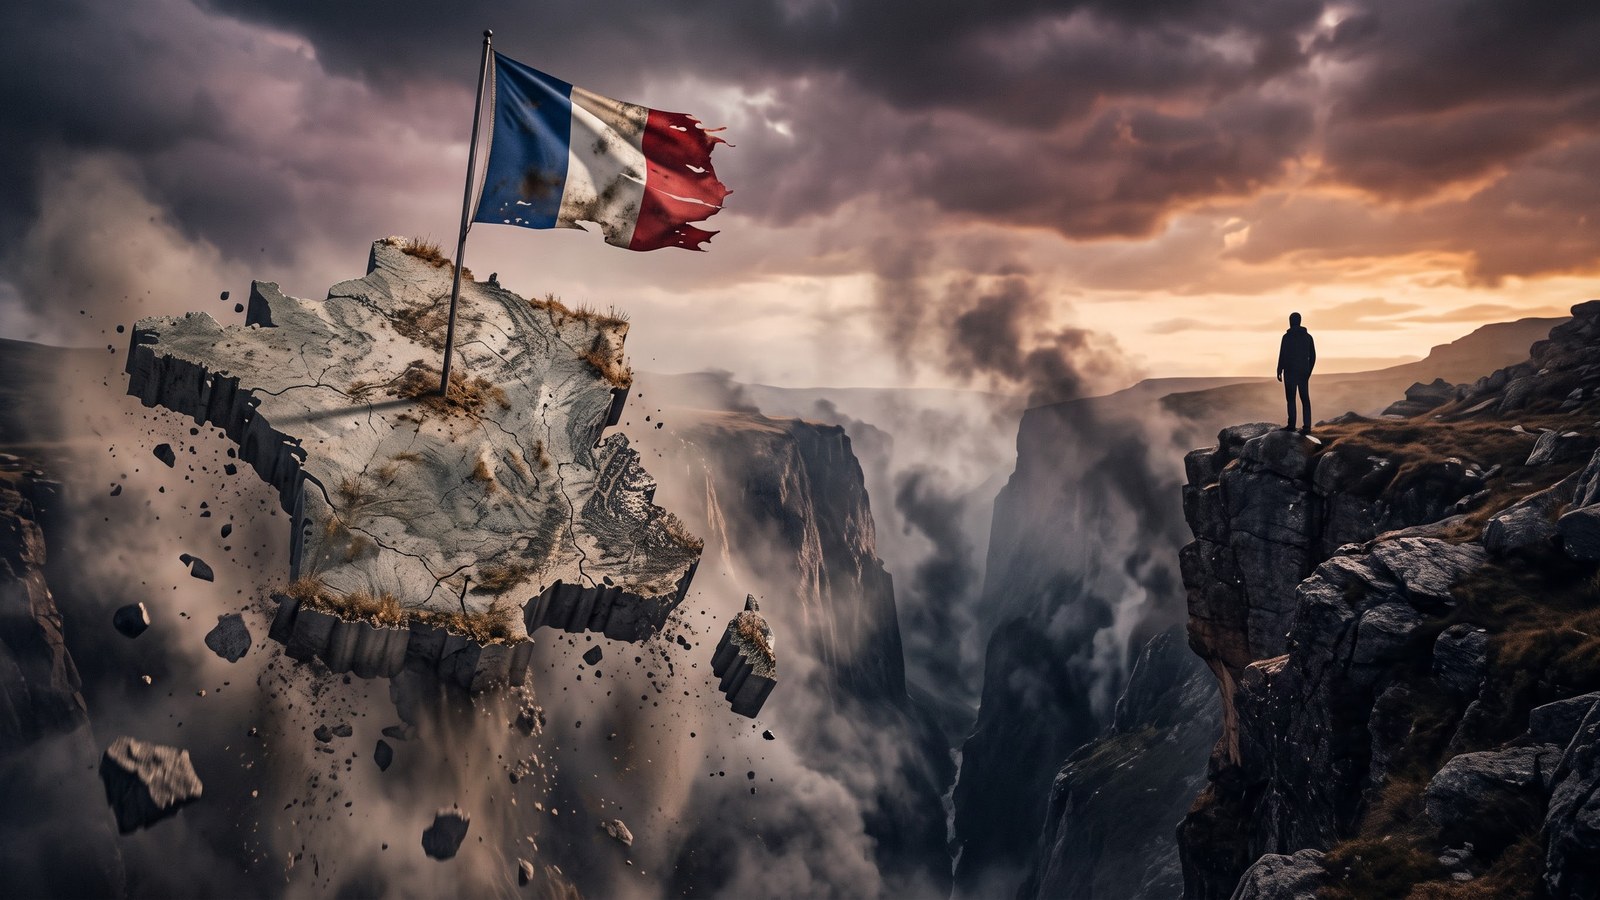
A strained budget, social unrest, external shocks, and a technological lag: can France avoid stalling by the summer of 2027, or will its six vulnerabilities feed into one another?
Publié le 21 octobre 2026
Share:
The facts
The point, in plain terms
France is grappling with a record deficit, sluggish growth, and mounting social anger ahead of the 2027 presidential election.
The French state is spending far more money than it brings in, running a deficit of 5.4% of GDP that is much higher than those of its European peers. The government is seeking to find €54 billion in savings, but inflation and fuel costs are weighing heavily on households. If the budget stalls or interest rates spike, the country will have to spend more on debt interest instead of funding schools or hospitals.
To understand France’s financial situation, one must first distinguish between two concepts often confused by the general public. The budget deficit* represents the financial shortfall over a single year, when government spending exceeds tax revenues. Public debt*, on the other hand, measures the total accumulation of all past unpaid borrowing. In 2026, France’s deficit is expected to reach 5.4% of GDP, a clear deterioration compared to 5.1% in 2025. Meanwhile, total debt is now hovering near 120% of national wealth, placing the country under close scrutiny from global financial markets.
This fiscal trajectory isolates France within the European Union. While Germany posts a deficit contained at 1.0% of GDP and Spain at 2.6%, Paris carries the heaviest budget shortfall among the eurozone’s major economies, ahead of Italy at 4.2%. To curb this drift, the government led by Sébastien Lecornu has presented a draft budget for 2027 outlining total savings and revenue measures of €54 billion. The official goal is to bring the annual deficit down to 5% of GDP. Without these spending cuts and tax hikes, the baseline deficit would risk spiraling toward 6.5% of GDP — an unsustainable level for the country’s creditworthiness.
Understanding it
How does a 5.4% budget deficit affect daily life in France?
A high deficit is like a household that borrows money every month just to buy groceries. To plug this shortfall of 5.4% of GDP, the state must borrow on financial markets. When interest rates rise, interest payments alone cost an additional €10 billion per year, depriving public services of vital resources.
The second front involves real economic activity, which is showing clear signs of slowing down. Insee recently downgraded its growth forecast for 2026 from 0.7% to just 0.4% growth. Activity is treading water quarter after quarter, weighed down by inflation* expected at 2.9% by year-end and a 0.4% decline in household purchasing power. This slowdown weighs heavily on employment, particularly among younger people. Youth unemployment (ages 15–24) climbed to 21.6% in the second quarter of 2026, fueling a strong sense of precariousness and stalled prospects among younger generations.
This sluggish economic climate is fueling growing social frustration across the country. According to an Odoxa poll, 88% of French people consider the outbreak of a new protest movement on the scale of the yellow vests to be possible. Following high school blockades that began on September 17, 2026, rising fuel prices are crystallizing grievances among households reliant on their cars for work. Nearly one in two French citizens reports feeling the bite of fuel costs in their daily budget. The government finds itself caught in a vise between public demands for price caps and the strict mandate to cut public spending.
On top of these domestic tensions comes an external global energy shock. The World Bank expects energy prices to surge by +24% in 2026, driven directly by the war in Iran and vessel disruptions in the Strait of Hormuz*. One-fifth of the world’s crude oil passes through this strategic maritime chokepoint. Because France imports virtually all of its fossil fuels, every rise in world prices inflates import costs, fuels consumer price increases, and compresses corporate margins, directly hindering productive investment across the country.
Understanding it
Why do tensions in the Strait of Hormuz directly impact fuel pumps in France?
The Strait of Hormuz is a narrow waterway through which 20% of the world’s oil passes. When conflict disrupts this passage, global crude supply tightens instantly. Prices surge, and French refineries pass these extra costs directly on to the price of fuel at every gas station.
Finally, the country’s future competitiveness is undermined by a worrying lag in tech adoption. According to a Cisco study, only 4% of French companies consider themselves fully ready to deploy artificial intelligence, compared to an 8% European average and 22% in Sweden. This structural weakness threatens long-term productivity gains. With the first round of the presidential election approaching on April 18, 2027, France is walking a tightrope: a parliament lacking an absolute majority complicates the passage of reforms, while debt servicing absorbs billions of euros desperately needed for public services.
2026 budget deficit (projection)5.4% of GDP Up vs. 5.1% in 2025
France 2026 growth (Insee revision)0.4% Revised downward (0.7% → 0.4%)
Les chiffres
Le déficit français se situe parmi les plus élevés de la zone euro à l'automne 2026.
France
5,4 %
Allemagne
1,0 %
Espagne
2,6 %
Italie
4,2 %
Royaume-Uni
5,1 %
Source : projections Insee, Eurostat et Banque de France, automne 2026
France facing the risk of a downward spiral by summer 2027
What we're assessing
FavorableUn compromis budgétaire et une détente sur le pétrole stabilisent les comptes avant 2027.
StableUn budget voté de justesse évite la crise financière sans régler les blocages de fond.
DégradéLe blocage politique et la flambée des taux d'intérêt précipitent le pays dans la récession.
Favorable
25%
Likely
A budget compromise is reached and the oil shock eases
First scenario: the government manages to pass its 2027 budget in the National Assembly through targeted concessions with opposition parties, without facing a fatal vote of no confidence. In practice, the bulk of the €54 billion in spending cuts and savings is implemented, reassuring international investors and stabilizing French borrowing costs. At the same time, geopolitical tensions in the Middle East subside following a diplomatic deal on Iran, enabling a rapid drop in oil prices. Inflation falls back below the 2% mark, restoring household purchasing power and defusing social unrest over fuel costs.
Compared to the other two trajectories, this favorable outcome relies on an alignment of positive domestic and global factors. It averts the spiral of distrust threatening public finances and allows growth to rebound toward 0.9% in the first half of 2027. This scenario would nonetheless remain fragile, as it depends heavily on international diplomacy and a temporary political truce ahead of the presidential election.
Indicators affected
Déficit public 2026 (projection)5,0 % du PIB↓5,4 % du PIB
Croissance France 2026 (révision Insee)0,9 %↑0,4 %
The France angleThe fiscal burden is shared, energy bills decline, and France preserves its financial credibility. ↑ Rather favorable for France.
Stable
45%
Likely
The budget narrowly passes, but economic vulnerabilities persist
Second scenario: the budget bill is adopted late after protracted parliamentary negotiations, but at the cost of substantial watering down of the initially planned savings. In practice, the public deficit falls only very slowly, remaining above 5.1% of GDP, while debt continues to climb toward 121% of national wealth. Energy prices remain high without surging further, keeping inflation around 2.5%. Strikes and roundabout blockades erupt sporadically without paralyzing the country’s activity, while businesses scale back youth hiring.
Unlike the full-blown crisis scenario, France avoids a banking panic and continues to raise funds on the markets at manageable interest rates, albeit higher than Germany’s. This middle-ground scenario reflects an economy running in slow motion, with growth stuck between 0.5% and 0.7% per year. The country would thus defer the most painful trade-offs until after the April 2027 presidential election.
Indicators affected
Déficit public 2026 (projection)5,2 % du PIB↓5,4 % du PIB
Croissance France 2026 (révision Insee)0,6 %↑0,4 %
The France angleThe country avoids an immediate financial collapse but accumulates heavy investment backlogs for the future. ↓ Rather unfavorable for France.
Degraded
30%
Likely
Government toppled, bond yields spike, and street protests paralyze the country
Third scenario: the National Assembly passes a vote of no confidence against the government over the 2027 budget, plunging the state into an unprecedented institutional crisis that forces the use of emergency finance bills. In practice, rating agencies downgrade France’s sovereign credit rating, pushing 10-year borrowing costs above 5% and immediately driving up debt service payments. In the streets, anger over rising fuel prices turns into a widespread Yellow Vests-style mobilization, blockading oil depots and major transport arteries amid persistently high oil prices.
Unlike the other two hypotheses, this political and social shock plunges the French economy into a sharp recession accompanied by cascading corporate bankruptcies. Uncertainty freezes hiring and pushes overall unemployment above 9%, while the 2027 presidential campaign opens amid total distrust in public institutions. Such deterioration could force authorities to implement even harsher emergency spending cuts across public budgets.
Indicators affected
Déficit public 2026 (projection)6,2 % du PIB↑5,4 % du PIB
Croissance France 2026 (révision Insee)-0,3 %↓0,4 %
The France angleA major fiscal crisis and persistent disruptions erode purchasing power and employment for millions of households. ↓ Rather unfavorable for France.
Ordres de grandeur indicatifs pour les 3 scénarios ci-dessus, estimés avec l'information disponible à la publication et réévalués si la situation change — jamais des prévisions garanties. Learn more about our method → · How to read a probability →
Key takeaways
France must determine whether it can restore its public finances and quell social unrest before the 2027 presidential election, or whether its imbalances will worsen.
The budget deficit is set to hit 5.4% of GDP in 2026 alongside growth slowing to 0.4%, while youth unemployment stands at 21.6% and energy costs surge 24% due to international tensions.
No swift turnaround in sight: our most likely scenario (45%) sees the budget passed with difficulty and the deficit remaining above 5%, compared to an open crisis scenario (30%) and an easing scenario (25%).
The final parliamentary vote on the budget bill by December 31, 2026, and pump price trends will serve as a decisive test for the country’s stability.
Fairly negative
Our assessment of the impact for France: fairly negative.because the political gridlock and fiscal stagnation scenarios together account for a 75% probability by summer 2027.
Si tu devais retenir 1 chose
Avec un déficit public attendu à 5,4 % du PIB en 2026 et une croissance ralentie à 0,4 %, la France cherche à économiser 54 milliards d'euros pour éviter un décrochage financier.
Don't miss the next edition:
For those new to the topic
Quick glossary
budget deficit
The negative gap recorded over a single year between the expenditures and revenues of all public administrations.
public debt
The total cumulative amount of borrowings incurred over time by the central government and social security system to finance their deficits.
inflation
A general and sustained increase in the prices of goods and services, which reduces the amount of goods and services a given sum of money can purchase.
Strait of Hormuz
A strategic strait in the Middle East connecting the Persian Gulf to the open ocean, through which one-fifth of the world’s crude oil passes.